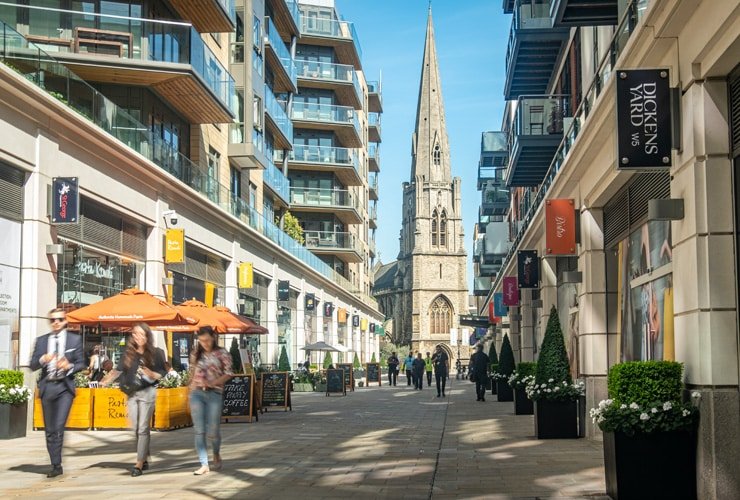
Walk down The Broadway on a weekday morning and you’ll notice the estate agents’ windows look a little different from a couple of years ago, with more reduced listings and asking prices that seem to have lost some of their nerve. Ealing hasn’t crashed, and it’s unlikely to. But higher borrowing costs have taken the heat out of a market that ran hot for the best part of a decade, and for anyone sitting on a deposit, the question of whether to buy is starting to feel less theoretical.
That’s especially true for would-be landlords, because a lower purchase price changes the maths on rental yield in a way that’s hard to ignore. Before committing, most sensible investors sit down with experienced ealing letting agents to test what a property would actually let for, rather than trusting portal averages. And that caution makes sense, since cheaper doesn’t automatically mean better value once mortgage rates, tax and regulation are factored in.
Why Prices Have Cooled in W5 and Beyond
Ealing’s growth over the past fifteen years was built on solid foundations: good schools, green space like Walpole Park and Pitshanger Park, and transport links few outer London boroughs can match. None of that has gone anywhere. What changed was the cost of money, and once mortgage rates climbed sharply from late 2022, buyers simply couldn’t stretch as far as they once did.
Family houses on the pricier streets around Ealing Common and the Brentham Garden Suburb have generally held up better than flats, a pattern you’d see across much of London. Flats, particularly in blocks where service charges have crept up, have felt more pressure. That split is worth paying attention to, because flats are usually where buy-to-let investors start looking.
The Rental Side of the Equation
Here’s where Ealing gets more interesting. While sale prices have softened, rental demand across west London has stayed stubbornly firm, and it isn’t hard to see why. The Elizabeth line, which stops at Ealing Broadway, West Ealing and Hanwell, has put Bond Street roughly a quarter of an hour away, and that’s reshaped who wants to live here.
Tenants now include West End and City workers who’d once have looked closer in, alongside staff at Ealing Hospital, students and lecturers at the University of West London, and people commuting to Park Royal. That mix gives landlords a broad pool to draw from. It also means different pockets suit different renters, with Northfields and South Ealing on the Piccadilly line attracting one type of tenant and flats near Ealing Broadway attracting another.
So is the gap between softer prices and steady rents a genuine opportunity? In some cases, yes. A flat bought today for less than it would have fetched in 2022 may well produce a better gross yield, provided the rent holds, but gross yield is only the starting point, and Ealing has never been a high-yield area compared with much of the Midlands or the North.
The Costs That Quietly Eat Into the Numbers
Buying an additional property in England now carries a 5% stamp duty surcharge on top of standard rates, following the increase in October 2024, and on a London purchase that’s a painful sum. Individual landlords also can’t deduct mortgage interest as an expense the way they once could, receiving a basic rate tax credit instead. For anyone borrowing heavily, those two factors alone can turn an attractive yield into something fairly thin.
Then there’s regulation, which is arguably the bigger shift. The Renters’ Rights Act, which became law in October 2025, has abolished section 21 “no fault” evictions and moved all tenancies onto a rolling periodic footing, with the main changes taking effect from 1 May 2026.
Anyone weighing up a purchase should read the government’s Renters’ Rights Act guidance for landlords before making an offer, since it sets out what’s now required from day one. Ealing Council also runs its own licensing schemes for HMOs and privately rented homes in a number of wards, so checking whether an address needs a licence should happen early too.
Where the Real Opportunities Might Be
Honestly, the best buys in Ealing right now probably aren’t the ones with the biggest price cuts. A flat that’s been reduced three times may have a problem the listing doesn’t mention, whether that’s a short lease, a hefty service charge or unresolved questions about an older block. The more promising deals tend to be well-placed properties where the seller simply needs to move and is pricing realistically.
West Ealing and Hanwell, generally speaking, offer lower entry prices than central Ealing while still sitting on the Elizabeth line, and that combination isn’t easy to ignore. Acton, just to the east, has seen a lot of new-build supply, which can hold down rents in the short term but also draws tenants into the wider area. Homes close to stations more often than not let faster, and void periods, even brief ones, can undo a year of careful budgeting.
There’s also a case for thinking about what tenants want rather than what investors usually buy. Two-bedroom flats with outdoor space, or small houses suited to sharers, tend to attract longer lets. And under the new rules, a tenant who stays for years is worth rather more than one who leaves after twelve months.
Who This Market Actually Suits
Ealing arguably favours patient landlords with modest borrowing over those relying on quick capital growth. If you’re buying with cash or a small mortgage, the current softness could mean securing a good property in a strong rental area at a price that looked out of reach two or three years ago. That’s not nothing. But if the plan depends on prices bouncing back quickly, the numbers become much harder to defend.
None of this means ruling the area out, and to be fair, few London boroughs combine Ealing’s transport, schools and green space with such a mixed tenant base. It just means going in with realistic expectations, a proper contingency fund and a clear view of how the new tenancy rules will shape the way you manage the property.
Final Thoughts
What’s happening in Ealing probably says more about the direction of buy-to-let generally than about one borough. The era when landlords could buy almost anything in a well-connected London suburb and let rising prices do the heavy lifting looks to be over, at least for now. What replaces it is a slower, more considered kind of investing, where yield, tenant quality and compliance matter as much as the purchase price.
For Ealing, that shift may turn out to be a quiet advantage. The things that draw tenants here aren’t going anywhere, and the Elizabeth line’s effect on the area is arguably still settling in. Landlords who treat the current dip as a chance to buy carefully rather than cheaply may find, a few years from now, that they picked a better moment than it felt at the time.

